Selling Your Condo in {Locaton} and Buying a House at the Same Time
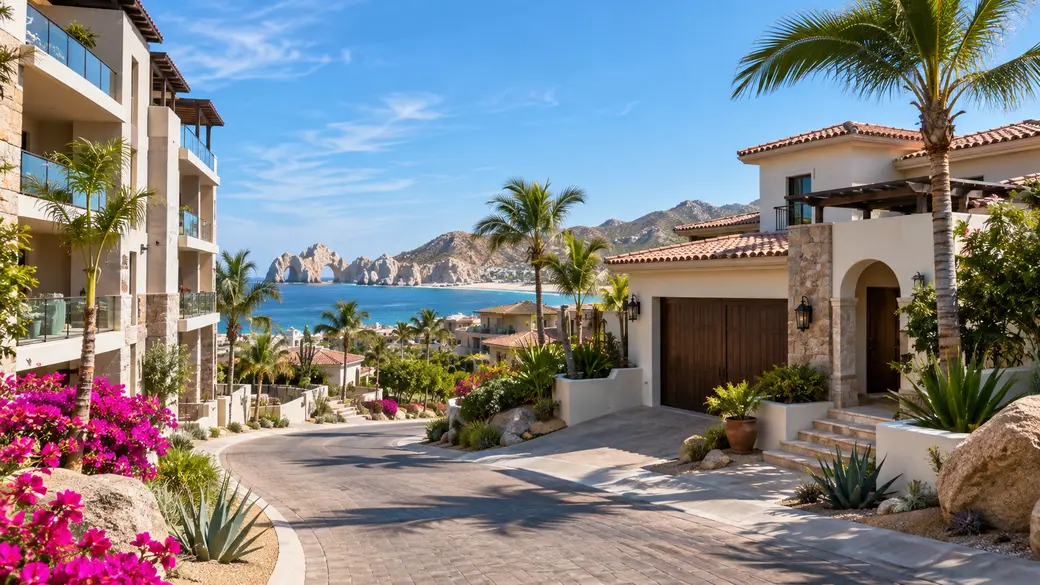
Selling your condo in Cabo San Lucas and buying a house at the same time is achievable when both transactions follow one shared timeline. That means clear deadlines and a backup plan for a delayed closing. Cabo San Lucas is a city and municipal delegation within the Municipality of Los Cabos, Baja California Sur, Mexico, rather than a separate county-level jurisdiction (Los Cabos Municipal Tourism Directorate).
The most reliable approach is to begin before your condo is listed:
- Identify the proceeds you expect to use for the house purchase.
- Organize property and condominium records.
- Decide how much overlap in ownership costs you can manage.
A coordinated sale and purchase can support one direct move, but it requires each party to understand the dates, conditions, and alternatives.
Buy First or Sell First?
Selling first is usually the lower-risk path because it establishes the funds available for your next home before you commit to a purchase.
For condo owners, a completed sale gives a clearer view of proceeds after several deductions:
- Closing costs
- Condominium obligations
- Any loan payoff
- Mexican capital gains tax, which the notary withholds at closing
A completed sale can also make a house offer easier to present, because your purchase no longer depends on the condo finding a buyer.
Buying first can make sense when you have sufficient liquidity, a dependable financing plan, and a house that fits your needs. The tradeoff is carrying two properties if the condo sale takes longer than expected. That may mean overlapping condominium fees, utilities, insurance, maintenance, and payments.
Timing deserves a realistic view. Across Los Cabos, condos averaged 267 days on market in the 12 months ending August 2026 and closed at an average of 95.9% of final asking price. August 2026 included 1,087 active condo listings. With that much competing inventory, a buy-first plan should assume the condo may take months, not weeks, to sell.
Source: aggregated MLS listing data, pulled October 5, 2026, for the 12 months ending August 2026.
| Approach | Funds certainty | Risk of carrying two properties | Temporary housing need | Often fits owners who |
|---|---|---|---|---|
| Sell first | Higher, because sale proceeds are known | Lower | Possible between closings | Prefer a conservative budget and a confirmed purchase range |
| Buy first | Lower until the condo closes | Higher | Usually lower if the new house is ready | Have liquidity and do not want to miss a specific home |
| Coordinate both closings | Depends on both contracts staying on schedule | Moderate | Lower when timing aligns | Have a market-ready condo and flexible parties on both sides |
A third option is to coordinate both closings with flexibility built into the contracts. This can reduce moving disruption, although it still needs a contingency plan for a change in either transaction.
A realistic price range and estimated net proceeds should guide the decision. A current valuation of your condo based on recent comparable sales in your building is the most useful starting point.
Estimating Your Net Proceeds
Your available funds depend on residency status as much as on sale price. Under Mexico's income tax law, the options differ for residents and non-residents.
Non-resident sellers generally choose between two options:
- Tax of 25% on the gross sale price, with no deductions
- Tax of 35% on the net gain after allowable deductions, which requires a legal representative in Mexico
Mexican tax residents selling their primary home may qualify for an exemption of up to 700,000 UDIs (Mexico's inflation-indexed units), once every three years, with proof of residence.
Documented purchase costs and improvement receipts can make a meaningful difference to the result. Run your numbers with the notary and a qualified tax adviser before you set a purchase budget for the house.
Condo-Specific Timing Factors
Condo-specific timing factors can extend a buyer's review period, so the most useful documents should be gathered before the listing launches.
Buyers commonly ask for:
- Homeowners association rules
- Current fee information
- Building policies
- Meeting records
- Maintenance updates
- Parking details
- Information about planned work that could affect future costs
Requirements can vary between developments in Cabo San Lucas, from beachfront condo buildings near Médano Beach to complexes closer to the marina. An early document review helps identify missing items before they affect the purchase timeline.
Prepare a working file that includes:
- HOA rules, contact details, and current fee statements
- Confirmation of fee payment status
- Parking, storage, amenity, and access information
- Available records on building maintenance or special assessments
- Rental and occupancy policies, where applicable
- Move-in and move-out procedures set by the building
- Your bank trust (fideicomiso) documents and predial receipts
Different Cabo San Lucas condominium developments may also use their own property management procedures for move reservations, guest registration, deposits, loading access, and use of common areas. Review the applicable building materials early so those requirements can be included in the sale and moving schedule.
For international owners, the ownership and closing structure also deserves early attention. Non-Mexican buyers typically hold residential property near Mexico's coast through a fideicomiso bank trust. The Mexican government explains that this structure allows the use and enjoyment of qualifying property in the restricted zone through a public deed (Secretaría de Relaciones Exteriores). In a simultaneous sale and purchase, you will likely be transferring or cancelling one trust while setting up another. The details of how foreign buyers hold property are worth reviewing early. The appropriate attorney, notary, and closing professionals should handle the particulars of the transaction.
A complete condo package reduces repeated requests after an offer arrives. It also gives your team more time to coordinate the sale date with the timing of the house purchase.
Contingent Offers
A contingent offer makes your house purchase dependent on an agreed milestone in your condo sale.
The milestone might be an accepted contract on your condo, a completed closing, or another clearly defined event. Whether a seller accepts those terms depends on:
- The strength of your condo listing
- Competing interest in the house
- The available timeline
- The certainty of your financial plan
A well-structured contingent offer should address practical questions before they become last-minute problems:
- Which condo-sale event must occur before the house purchase proceeds?
- What are the deadlines for each transaction?
- What happens if the condo closing is delayed?
- May the house seller continue marketing the property?
- What funds or alternative arrangements are available if the condition must be removed?
A contingency is not automatically a weakness. It is a tool for assigning timing risk clearly. The better the documentation, pricing strategy, and communication around the condo sale, the easier it is to present a credible plan to the house seller.
Bridge Financing and Seller Financing
Bridge financing can provide temporary purchasing capacity before your condo closes. It should only be considered with a defined repayment plan and professional guidance.
This type of arrangement covers the period between buying the house and receiving proceeds from the condo sale. It may be useful when an owner wants to act on a suitable house without first moving into temporary accommodation.
The added flexibility comes with added exposure. Several costs can affect the outcome:
- Interest charges
- Fees
- Delayed closings
- Currency considerations
- Overlapping ownership costs
Buyers drawing on U.S. home equity for a bridge should note that borrowing costs remain elevated. The average U.S. 30-year fixed mortgage rate was 7.24% for the week ending October 29, 2026, according to the Freddie Mac Primary Mortgage Market Survey. Before relying on short-term financing, test the budget against a longer-than-expected condo sale period rather than assuming both transactions will close exactly as planned.
In some cases, seller financing on the house can serve a similar purpose, giving you time to close the condo sale before the balance is due. Any such arrangement should be structured with legal guidance.
For buyers and sellers working across borders, Mexican transaction structures can differ from those commonly used in the United States or Canada. Coordination among qualified financial, legal, notarial, and closing professionals is particularly important when ownership documents and funds must line up across two connected transactions.
A sound bridge strategy includes an expected sale timeline, conservative proceeds assumptions, and cash reserves for an extended overlap.
Rent-Backs and Flexible Closings
Rent-backs and flexible closing dates can create a practical buffer when the condo sale and house purchase do not settle on the same day.
Rent-back. A rent-back generally allows the seller to remain in the condo for a short, agreed period after closing. It may provide time to complete the house purchase, schedule movers, or prepare the new property without rushing through a same-day handoff.
Flexible closing dates. These can serve a similar purpose. If the condo buyer has scheduling flexibility, the parties may be able to choose a closing date that better supports the expected completion of the house purchase.
Any occupancy or timing arrangement should be documented carefully and reviewed by the appropriate local professionals. Before agreeing to a rent-back or delayed possession period, clarify:
- The exact possession date and time
- Any payment terms
- Responsibility for utilities and HOA fees
- Insurance responsibilities during occupancy
- Access rules for movers
- The final key and property handoff process
These details are operational, but they can determine whether the transition feels orderly or rushed.
Coordinating Moving Day
Coordinating moving day starts with your condo building's rules, especially where elevator use, loading access, security procedures, or permitted moving hours apply.
Many Cabo San Lucas condominium communities require advance notice for moves. Building management may have:
- Designated loading areas
- Elevator reservation procedures
- Access requirements
- Deposits
- Time restrictions
Confirm those requirements when your likely closing window becomes clear, not after movers have been booked. If the house is in a gated neighborhood such as Pedregal, confirm the community's access and delivery procedures as well.
Create one shared checklist for the condo sale, house purchase, and move. It should cover:
- The closing sequence
- Key delivery
- Utility transfers
- Insurance changes
- Mover availability
- Storage options
- Essential items needed if access to either property shifts by a day or more
The steps between an accepted offer and closing day give a useful backbone for that checklist.
It is wise to prepare for a gap even when both closings are scheduled for the same day. A short-term storage plan, a bag with essentials, and a flexible moving crew can keep a minor scheduling change from becoming a major disruption.
A coordinated plan prevents a double move or two payments by connecting the condo sale, house purchase, financing choices, and moving logistics from the beginning.
Selling your condo in Cabo San Lucas and buying a house at the same time does not require perfect timing. It requires:
- A realistic sequence
- Organized condominium documentation
- Clear purchase conditions
- A workable backup plan
When the sale and purchase are treated as one connected project, you are better positioned to protect your budget and reduce unnecessary disruption.
Planning a Condo Sale and House Purchase in Cabo San Lucas?
Michael Nicol is the broker and co-owner of Cabo 4 Sale Real Estate. The brokerage has worked with buyers and sellers from the same Cabo San Lucas office since 2005, and Michael brings nearly 30 years of Los Cabos real estate experience.
Because both sides of the move run through the same team, pricing, offer terms, the bank trust, and both closings stay on one timeline. They are coordinated with long-standing local attorneys, notaries, inspectors, and escrow professionals. Support continues after the move, too.
Call or text +52 (624) 136-6005, email broker@cabo4sale.com, or reach out through the contact page.
FAQ
Can I buy a house before my condo sells in Cabo San Lucas?
Possibly. Buying before your condo closes may work if you have adequate liquidity, suitable short-term financing, or purchase terms tied to a defined stage of the condo sale. With condos averaging 267 days on market across Los Cabos over the past year, plan for the possibility of carrying both properties for several months.
How much tax will I pay when I sell my condo?
It depends on residency. Non-resident sellers are generally taxed at 25% of the gross sale price or 35% of the net gain with a legal representative in Mexico. Mexican tax residents may exempt a primary home sale up to 700,000 UDIs once every three years. The notary withholds the tax at closing.
Do HOA documents slow down a condo sale?
Yes. Late or incomplete HOA materials can delay a buyer's review. Providing available rules, fee information, management contacts, maintenance records, and building procedures early gives buyers a clearer picture of the condominium and can reduce follow-up requests.
What is a rent-back?
A rent-back allows you to stay in the condo briefly after the sale has closed. It can give you additional time to finalize the house purchase, complete the move, or prepare the new home without requiring both transactions to occur on the same day.
Do I need to reserve the elevator to move?
Many condominium buildings require an elevator reservation or follow specific moving procedures. Contact management early to confirm available hours, loading access, security requirements, elevator availability, and any applicable deposits or fees.
Recent Posts
GET MORE INFORMATION